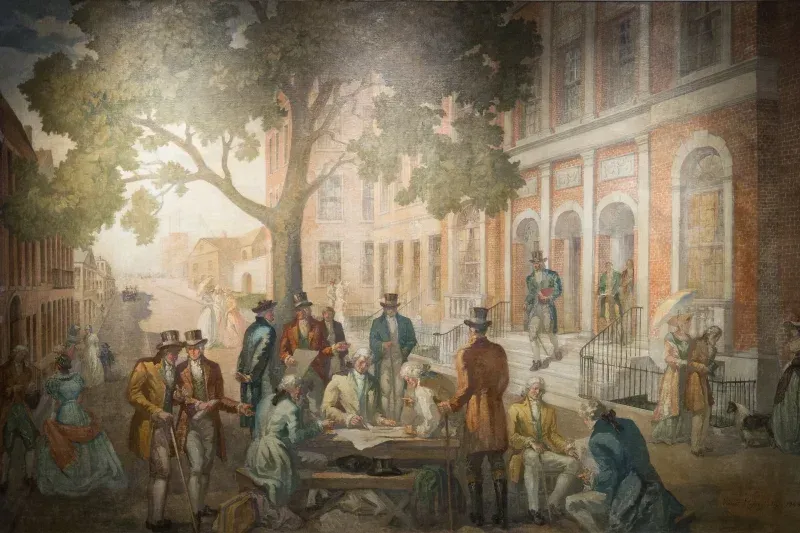
On July 4, 2025, President Trump signed the One Big Beautiful Bill Act into law. For business owners, it delivers both permanent enhancements to depreciation and expensing and expanded tax credits, along with a significantly broader capital‑gains exclusion for certain C Corporation stock.


1. Permanent Bonus Depreciation & Increased Expensing

  • 100 Percent Bonus Depreciation Becomes Permanent
    Under current law, bonus depreciation phases down 20 percent per year after 2023. The new law makes 100 percent immediate expensing permanent for qualified property placed in service after January 19, 2025. This provision may allow eligible businesses to reduce taxable income in the year of acquisition, depending on their specific circumstances.
  • Higher Section 179 Expensing Threshold
    The maximum annual Section 179 deduction rises from $1 million to $2.5 million, with the phase‑out threshold increasing from $2.5 million of equipment purchases to $4 million (indexed for inflation after 2025). This change may enable more small to mid-sized firms to expense the full cost of qualifying assets in the year purchased.


2. Expanded Research, Workforce & Energy Credits

  • R&D Expense Deduction Restored
    Previously, domestic research costs had to amortize over five years. The Act reinstates immediate expensing of R&D outlays and allows eligible small businesses (≤ $31 million in gross receipts) to elect retroactive deductions for 2022–2024. This may improve cash flow for innovation-focused firms.  
  • Business Interest Deduction Cap Raised
    For 2025 and beyond, “adjusted taxable income” for purposes of the interest‑expense limitation will exclude depreciation, amortization, and depletion. This change may allow businesses with high capital costs to deduct a larger share of interest in the current year.
  • Paid Family & Medical Leave Credit Made Permanent
    The credit, which covers up to 25 percent of wages paid to employees on qualified leave, now becomes permanent. It also expands to include family‑leave insurance premiums, potentially lowering the net cost of offering leave benefits.
  • Other Notable Credit Extensions & Increases
  • 50 percent deduction for business‑meal expenses remains permanent.
  • Enhanced advanced‑manufacturing investment credit rises from 25 percent to 30 percent for property placed in service after December 31, 2025.
  • Employer child‑care credit increases to $500,000 (40 percent of expenses) and adds a small‑employer credit up to $600,000 (50 percent of expenses).
  • Student‑loan assistance exclusion becomes permanent and indexed for inflation.
  • Paid Overtime Tax Credit of up to $12,500 ($25,000 joint filers) introduced.
  • New Markets Tax Credit and certain rural‑loan interest exclusions are extended or introduced.


3. Enhanced Qualified Small Business Stock (QSBS) Exclusion

According to Husch Blackwell, the Act confirms three major updates to IRC § 1202 that may influence your choice of entity selection and capital‑gains planning (Husch Blackwell):


  1. Tiered Holding‑Period Exclusions
  • ≥ 3 years held → 50 percent exclusion
  • ≥ 4 years held → 75 percent exclusion
  • ≥ 5 years held → 100 percent exclusion
  1. Higher Per‑Issuer Cap
  • The exclusion limit increases from the greater of $10 million or 10× basis to $15 million, with annual inflation adjustments.
  1. Increased Gross‑Asset Threshold
  • Qualifying C Corps may now have up to $75 million in assets (up from $50 million), indexed for inflation.


These changes may make C Corporation status more attractive for startups and growth companies planning liquidity events three or more years out. However, the benefits depend on a variety of factors, including timing, structure, and exit strategy.


4. Next Steps for Business Leaders

Buttonwood Financial Group works with our clients to align their business and personal financial strategies. Here are a few ways we can support you in light of this new legislation;


  1. Model Your 2025 Tax Profile
  2. We’ll work with you and your CPA to project taxable income, evaluate bonus depreciation vs. Section 179 elections, and assess credit phase‑out impacts.
  3. Revisit Entity & Capital Structure
  4. We can coordinate with legal and tax professionals to evaluate whether the expanded QSBS expansion makes C Corp status more favorable for your long-term objectives.
  5. Time Major Purchases & Elections
  6. Strategically timing equipment or R&D investments may allow you to maximize deductions and credits in 2025.  
  7. Monitor IRS & Treasury Guidance
  8. As we have done for more than 20 years, we remain aware of regulations that may refine definitions, phase-in rules, or eligibility criteria – and keep you informed.


Let’s Talk Strategy

If you’d like to explore how these provisions might apply to your business or personal tax strategy, our Team stands ready to assist. We’ll work alongside your tax and legal advisors to ensure your plan is both compliant and aligned with your goals. Contact us today to learn more.


Please note: This summary is for informational purposes only and does not constitute tax or legal advice. Individual outcomes may vary. We recommend consulting with tax, legal, and other advisors before making any decisions. If you don’t already have these professionals in your network, please let us know as we work with many on a regular basis.


Sources:

1.      https://www.bizjournals.com/kansascity/news/2025/07/03/slew-of-small-business-tax-cuts-set-to-become-law.html

2.      https://www.huschblackwell.com/newsandinsights/one-big-beautiful-bill-act-expands-qualified-small-business-stock-exclusion

3.      https://www.congress.gov/bill/119th-congress/house-bill/1

Recent Buttonwood Articles

Estate planning documents representing family, legacy, and financial planning.
By Danielle Brown MSF, CFP® • September 28, 2026
The 2026 federal estate tax exclusion is $15 million per individual. Learn why being under the threshold does not make estate planning irrelevant.
Buttonwood Financial Group Investment Policy Committee May and June 2026 portfolio rebalance summary
By Jon McGraw, Investment Policy Committee Chair, Buttonwood Financial Group (Kansas City) • July 20, 2026
How our Investment Policy Committee approached the May & June 2026 rebalances: trimming equity risk, upgrading bond quality, and adding liquid alternatives.
Child placing coins into a piggy bank while learning about saving and financial responsibility.
By Danielle Brown, CFP MSF • July 7, 2026
What families should know about Trump Accounts eligibility, contributions, financial literacy. Child investment accounts may fit in broader financial plan.
By Jon McGraw • July 1, 2026
Beyond fees, DIY investing carries hidden costs — time, taxes, and coordination. A Kansas City wealth management perspective on when self-directed makes sense
SpaceX and Anthropic are filing for the two largest IPOs in history. Learn how index fund exposure,
By Kristy Wieland • June 10, 2026
SpaceX and Anthropic are filing for the 2 largest IPOs in history. Index fund exposure, 401(k) passive buying, and mutual fund holdings mean you may already own them
By Kristy Wieland • May 16, 2026
The Buttonwood Agreement: Where American Finance Took Root — and Why Our Name Exists The Buttonwood Agreement was a compact signed on May 17, 1792, by 24 stockbrokers and merchants beneath a buttonwood tree at 68 Wall Street in New York City. It established the rules of organized securities trading in America and laid the foundation for what would become the New York Stock Exchange. Buttonwood Financial Group takes its name directly from this founding moment; as a daily commitment to the integrity, transparency, and long-term thinking those original brokers put on paper. What was the Buttonwood Agreement, and why it still matters The Buttonwood Agreement came at a moment of crisis. The Panic of 1792, America's first speculative bubble and market collapse, had shattered public confidence in capital markets. Prominent financiers defaulted. Prices fell. Investors panicked. Alexander Hamilton worked to stabilize the system, but the lasting fix came from the professionals themselves. On May 17, 1792, 24 brokers gathered under a buttonwood (sycamore) tree outside 68 Wall Street and signed a two-sentence agreement: they would deal only with each other, charge a standard commission of one-quarter percent, and give preference to fellow signers in all negotiations. Simple. But the effect was transformative. By agreeing to hold a higher standard collectively, they rebuilt confidence in the market itself. The Buttonwood Agreement is widely regarded as the founding document of the New York Stock Exchange and of organized American finance. Why Buttonwood Financial Group carries this name Boutique wealth management firms are built on process and trust. When we named our firm Buttonwood Financial Group, the choice wasn't aesthetic; it was philosophical. Our name is a daily accountability measure; a reminder that the values those brokers signed onto in 1792 — integrity, structure, and responsibility — are exactly the values our clients deserve today. The families and individuals we serve aren't looking for surface answers and financial products. They're looking for an experienced team that has been tested across market conditions, that communicates honestly, and that approaches every client relationship from a fiduciary capacity in a long-term commitment. That's what an established boutique wealth management firm looks like in practice. What experience really means Experience in this industry isn't about credentials alone. It means you have been present with clients through market downturns and periods of uncertainty. You have worked alongside families through estate complexity, business transitions, and inheritance conversations. You have coordinated tax strategy, cash flows, and generational goals at the same time; because for most families, those things can't be separated. Our Team brings that depth to every engagement. Not because we're proud of our tenure, but because the people we serve deserve to work with real people whose judgment has been informed by real world complexity and a wide range of client circumstances. The values that haven't changed in 234 years The Buttonwood Agreement was forged in a crisis to restore confidence. That context mirrors what many clients feel when they first reach out to a firm like Buttonwood. The financial world is complex, opaque, and hard to navigate. Our commitment is to bring transparency, fiduciary responsibility, and honest communication to every relationship, the same values those brokers enshrined in 1792. Roots matter. They tell you where a firm stands when things get hard. On Buttonwood Agreement Day, we honor that founding moment, and recommit to carrying it forward. Connect with Buttonwood Financial Group If you're evaluating whether your current wealth management relationship reflects these values, we'd welcome the conversation. Our advisors work with individuals, families, and business owners on comprehensive, fiduciary-driven financial plans built around your long-term goals. Frequently Asked Questions What is the Buttonwood Agreement? The Buttonwood Agreement was a compact signed on May 17, 1792, by 24 stockbrokers and merchants in New York City. It established standardized rules for securities trading, dealing only among members, and charging a fixed commission. It is considered the founding document of the New York Stock Exchange. When is Buttonwood Agreement Day? Buttonwood Agreement Day is observed annually on May 17, marking the date the original agreement was signed in 1792 outside 68 Wall Street in New York City. Why is the Buttonwood Agreement significant in finance? The Buttonwood Agreement replaced chaotic, unregulated securities auctions with a system of structured, trust-based trading. It restored public confidence after the Panic of 1792 and established the foundational principles, integrity, accountability, and standardized commissions, that governed Wall Street for nearly two centuries. What does Buttonwood Financial Group do? Buttonwood Financial Group is an independent SEC Registered Investment Adviser. A boutique wealth management firm. The firm works with individuals, families, and business owners to provide both financial planning and investment management services. By serving as the primary financial advisor and administrator, Buttonwood is essentially acting as the family's "CFO" while the client remains as the family "CEO." Buttonwood strives to organize, formalize, implement, and monitor financial strategies consistent with clients' multi-generational goals and objectives. What makes a boutique wealth management firm different? Boutique wealth management firms typically offer more personalized service, deeper advisor relationships, and a fiduciary-first approach. Advisors and their support teams generally work with fewer clients and provide more integrated guidance and may reach a deeper level of strategy across investments, tax, business and estate planning, and financial planning. How do I choose an experienced financial advisor? We often see the following criteria: Look for advisors with a fiduciary obligation, verifiable credentials (CFP, CFA, or similar), a transparent fee structure, and experience working with clients whose situations are similar to your own. Confirm the advisor's registration status at adviserinfo.sec.gov. B uttonwood Financial Group is a registered investment adviser. The information provided in this article is for general informational purposes only and does not constitute investment, financial, tax, or legal advice. Past results are not indicative of future performance. All investing involves risk, including possible loss of principal. Please consult a qualified professional for advice specific to your situation.

Are you ready to explore the benefits of your very own Family CFO?
LET'S TALK

Buttonwood Services


About Buttonwood Financial Group